 Why Trust MoneySmart?
KrisFlyer credit cards are built for one thing: helping you turn your everyday spending into Singapore Airlines miles, without juggling conversion portals or paying transfer fees.
If you already fly SIA or Scoot a few times a year, or want to start building a serious miles balance, this guide walks you through how KrisFlyer credit cards work, the key cards to compare in 2026, and practical strategies to make sure those miles actually turn into flights (not just numbers in an app).
How Do KrisFlyer Credit Cards Work?
A KrisFlyer credit card is a co-branded card linked directly to your Singapore Airlines KrisFlyer frequent flyer account. Unlike a generic rewards or cashback card, these products are designed to feed miles straight into KrisFlyer, which you can later redeem for flights, upgrades, and other travel perks with SIA, Scoot, and partner airlines.
Direct miles instead of bank points
With a co-branded KrisFlyer card, your eligible spending earns miles that are automatically credited to your KrisFlyer account—you don’t have to log in to a rewards portal, convert points, or pay a miles transfer fee. Broadly, the earn structure looks like this:
Local spend: Most KrisFlyer cards pay around 1.1–1.3 miles per S$1 on local general spend.
Overseas or travel spend: Foreign-currency transactions and travel bookings often earn a similar or higher rate, depending on the card. For example, the KrisFlyer UOB Credit Card and AMEX KrisFlyer cards boost earnings on Singapore Airlines, Scoot, KrisShop, Kris+, and Pelago.
Bonus categories: Certain cards offer accelerated miles on dining, food delivery, online retail, transport, and travel bookings, sometimes contingent on hitting a minimum annual SIA Group spend.
Because miles are “KrisFlyer-ready” the moment they post, these cards particularly suit people who want to focus on one main airline ecosystem instead of juggling multiple partners.
Core perks: What do you get?
Most KrisFlyer co-branded cards share a few core benefits:
Benefit | Mechanics |
|---|---|
Automatic miles crediting | Earned miles post directly into your KrisFlyer account, so you don’t risk forgetting to convert bank points. |
Welcome bonus miles | New cardholders can unlock large blocks of bonus miles when they meet a minimum spend within the first 1–2 months. |
Travel insurance and perks | Many come with complimentary travel insurance, flight delay or baggage coverage, and sometimes extras like lounge visits or hotel night vouchers (especially on premium tiers). |
No miles conversion fees | For cards that credit directly to KrisFlyer, there’s no separate fee to transfer miles from bank to airline; the transfer happens automatically. |
Exact benefits differ by issuer and card tier, but the overall design is to make KrisFlyer the default home for your miles.
Eligibility Criteria: Who can apply?
Requirements are broadly similar to most entry-level air miles cards in Singapore:
Minimum age: 21 years old
Residency: Singapore Citizens, Permanent Residents, and eligible Foreigners
Income:
Typically S$30,000 annual income for Singaporeans/PRs
Higher thresholds (e.g. S$40,000+) are common for foreigners, depending on bank policy
Approval is still subject to each bank’s internal credit assessment and MAS responsible lending guidelines, so meeting the minimum income is necessary but not a guarantee.
Who should consider a KrisFlyer credit card?
KrisFlyer cards tend to make most sense if you:
Fly Singapore Airlines or Scoot at least occasionally and want to build miles in one ecosystem
Are a regular or aspirational traveller who values flights and upgrades more than cashback
Have moderate to high annual spend and can comfortably hit welcome bonus thresholds (e.g. upcoming travel, weddings, renovations, or big-ticket purchases)
Prefer to avoid the extra admin of converting bank points into airline miles and paying transfer fees
If you primarily fly on other alliances (e.g. oneworld or SkyTeam), or want flexible points across multiple airlines, you may be better off with non-KrisFlyer miles cards—which we’ll cover later.
KrisFlyer Credit Card Comparison (2026)
KrisFlyer credit cards aren’t one-size-fits-all. Some are tuned for entry-level flyers who want simple, direct miles; others are aimed at frequent travellers chasing status, hotel perks, and lounge access.
Below is a quick side-by-side of key cards, focusing on how quickly they earn miles and what perks come with them.
Card Name | Local MPD* | Overseas MPD* | Bonus Categories (Elevated MPD) | Notable Perks & Spend Exclusions | "Best For" |
|---|---|---|---|---|---|
1.2 | 1.2 | 3 mpd: SIA, Scoot, KrisShop, Kris+, Pelago; 2.4 mpd: dining, food delivery, online shopping/travel/transport (with min. S$1,000 qualifying SIA Group spend) | Exclusive Scoot benefits; no miles conversion fee | Everyday miles seekers; SIA/Scoot flyers | |
1.1 | Not stated** | 2 mpd: SIA, Scoot, KrisShop, Pelago, Grab (cap applies) | S$150 cashback at Singapore Airlines (min. spend S$12,000); free travel insurance | First-timers and value-maximisers | |
1.3 | Up to 2.2* | NA | 2x Priority Pass visits/year; S$27.25 miles transfer fee; conversion required | Flexible chasers; lounge access seekers |
MPD = Miles Per Dollar.
*American Express does not explicitly state overseas base rates, refer to card T&Cs for details.
Best KrisFlyer Miles Credit Cards
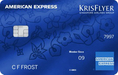
- on eligible Singapore Airlines & Scoot flight bookings, KrisShop & Pelago purchases, with no cap
- S$1 = 2 KrisFlyer miles
- on all other eligible purchases
- S$1 = 1.3 KrisFlyer miles
- directly credited into your KrisFlyer account
- KrisFlyer miles
- on eligible Singapore Airlines & Scoot flight bookings, KrisShop & Pelago purchases, with no cap
- S$1 = 2 KrisFlyer miles
- on all other eligible purchases
- S$1 = 1.3 KrisFlyer miles
- directly credited into your KrisFlyer account
- KrisFlyer miles
