Compare and Apply for Best Personal Loans in Singapore November 2026
Apply for top personal loan offers in Singapore from leading banks and licensed lenders online
Refine Your Results
We found 15 Personal Loans for you!


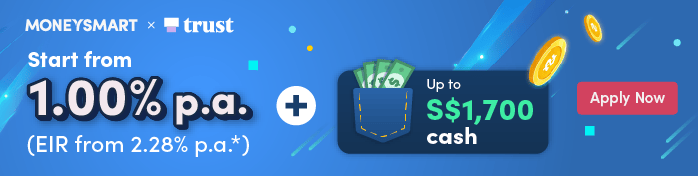
Sign up via MoneySmart and claim:
Up to S$1,700 Cash via PayNow OR 19,490 SmartPoints (enough to redeem the latest Apple iPhone 18 Pro and more) T&Cs apply.
Valid till 30 Nov 2026



New-to-loan customers for Maribank Instant Loan are eligible for 100% interest cashback if they successfully drawdown a 1 month tenure loan! Enter promo code FREE1NEW at point of application. T&Cs apply.
Enjoy attractive interest rates from as low as 1.28% p.a. (EIR from 1.92% p.a.) and zero processing fees* for any loan amount.
Valid till 31 Dec 2026

Valid till 30 Nov 2026








Disclaimer: At MoneySmart.sg, we strive to keep our information accurate and up to date. This information may be different than what you see when you visit a financial institution, service provider or specific product’s site. All financial products and services are presented without warranty. Additionally, this site may be compensated through third party advertisers. However, the results of our comparison tools which are not marked as sponsored are always based on objective analysis first.
Why Trust MoneySmart 💡
MoneySmart helps Singaporeans compare verified financial products side-by-side, so you find the best credit card, loan, insurance and other personal finance products for your needs—before you apply, not after. As an MAS-licensed platform with over 15 years in the market and a 4.4/5 Google rating from more than 2,000 reviews, we surface exclusive sign-up bonuses and deals you won't find by going directly to a provider—with faster gift fulfilment and flexible redemption on top.
Personal Loans in Singapore: Compare Banks, Digital Banks and Licensed Moneylenders
A personal loan in Singapore is an unsecured loan you repay in fixed monthly instalments over months or years. Banks, digital banks, and licensed moneylenders all offer them, but their costs, tenures and eligibility rules differ widely.
This guide explains how personal loans work, what they really cost, and how to choose a legal lender that fits your budget. Thereafter, compare personal loans side-by-side on MoneySmart once you know what to look for.
MoneySmart Recommends: Which Bank Offers the Best Personal Loans in Singapore?
There's no single best bank for everyone. The right loan depends on whether you want the lowest effective interest rate (EIR), the fastest cash, a longer tenure or easier eligibility. As of November 2026, these personal loans stand out for different needs:
| ⭐ Best for | Personal loan | Interest rate | What to know |
|---|---|---|---|
| Competitive advertised rate | Standard Chartered CashOne | From 0.90% p.a. (EIR from 1.75% p.a.) |
Instant approval and cash via Singpass MyInfo No processing fee, but a S$199 first-year annual fee (not included in the EIR) Minimum annual income:
|
| No processing fee | UOB Personal Loan | From 1.00% p.a. (EIR from 1.93% p.a.) |
Processing fee waived on all tenures Instant cash from 8am to 9pm (Mon to Sat) into a UOB account Requires a UOB credit card or CashPlus account; no documents needed if you have one |
| Available for Malaysians | CIMB Personal Loan | From 1.00% p.a. (EIR from 1.94% p.a.) |
All rates published upfront; no CIMB account or card needed Minimum annual income:
|
| Existing DBS / POSB customers | DBS Personal Loan | From 1.00% p.a. (EIR from 2.32% p.a.) |
Instant approval and cash for DBS/POSB customers; loans approved after 11.45pm are credited the next day 1% processing fee Minimum annual income (if you don't have a DBS/POSB card or cashline):
|
| Existing Trust cardholders | Trust Instant Loan | From 1.00% p.a. (EIR from 2.28% p.a.) |
Approval and payout in about 60 seconds Requires a Trust credit card No processing fee, but a 0.88% first-year annual fee (included in EIR) Minimum $30,000 annual income |
| Longest tenure | HSBC Personal Loan | From 1.30% p.a. (EIR from 2.50% p.a.) |
Up to 7 years (most banks cap at 5 years) Up to 8 times monthly income (or S$100,000, whichever is lower) if you earn S$120,000 or more Requires an HSBC Personal Line of Credit (S$120 annual fee, first year waived) 1% processing fee (included in EIR); 2.5% early repayment fee |
| No fees, including early repayment | GXS FlexiLoan | From 2.99% p.a. (EIR from 5.65% p.a.) |
No processing, annual or early repayment fees Draw up to 10 loans from one credit line, each with its own tenure of 2 to 60 months Minimum $20,000 annual income |
| Fastest payout | Maribank Instant Loan | From 1.86% p.a. (EIR from 2.79% p.a.) |
Cash in your MariBank account within 10 seconds of approval Borrow from S$100, with tenures from 1 to 60 months No processing or annual fee Minimum S$30,000 annual income |
How a Personal Loan Works
| Type | How it works | Cost | ⭐ Best for |
|---|---|---|---|
| Personal loan | Lump sum repaid in fixed monthly instalments, with no collateral |
Banks: EIR from about 1.75% to 2.32% p.a. (e.g. Standard Chartered CashOne, DBS) Licensed moneylenders cost more |
Planned, one-off expenses |
| Line of credit | A standby credit limit you draw from and repay as needed, paying interest only on what you use | Around 20% to 24% p.a. on the amount you use (e.g. UOB CashPlus 20.9%, DBS Cashline 22.9%) | Ongoing or unpredictable costs |
| Secured loan | Backed by collateral such as property, a car or a fixed deposit | Usually lower rates and higher limits than unsecured loans, depending on the asset; you may lose the asset if you default | Large purchases |
| Payday loan | Short-term cash loan, usually from a licensed moneylender, repaid by your next salary | Up to 4% a month in interest (about 48% a year), plus an admin fee of up to 10% | Small, urgent sums only |
You can start your application on MoneySmart, which redirects you to the lender's site to complete it, usually with Singpass MyInfo. Many lenders, including the DBS Personal Loan, CIMB Personal Loan and Standard Chartered CashOne, offer instant approval. Once you get the cash, you repay by GIRO or monthly transfer.
💡 MoneySmart Tip: Personal loans suit planned, one-off costs such as renovations, weddings, or medical bills. They are not a fix for a recurring monthly shortfall.

Latest MoneySmart Promotions for Personal Loan in Singapore? (November 2026)
MoneySmart’s latest exclusive personal loan promotions give you more cashback, faster gift fulfilment, and lower rates than ever. Whether you’re planning a wedding, consolidating debt, or just need quick cash for a project, here are the current top personal loan deals — verified and updated.
MoneySmart Exclusive Personal Loan Offers 2026
| Personal Loan | Interest Rate | EIR | Promotion | Valid until |
|---|---|---|---|---|
| Trust Instant Loan | From 1.00% p.a. | From 2.28% p.a. | Sign up through MoneySmart to claim up to S$1,700 Cash or 19,490 SmartPoints, enough to redeem the Apple iPhone 18 Pro and more. | 8 Nov 2026 till 30 Nov 2026 |
| Trust Instant Loan (Foreigners) | From 1.00% p.a. | From 2.43% p.a. | Sign up through MoneySmart to claim up to S$1,700 Cash or 19,490 SmartPoints, enough to redeem the Apple iPhone 18 Pro and more. | 8 Nov 2026 till 30 Nov 2026 |
| MariBank Instant Loan | From 1.28% p.a | From 1.92% p.a. | New-to-loan customers for Maribank Instant Loan can receive 100% interest cashback on a 1-month tenure loan with promo code FREE1NEW. Enjoy interest rates from 1.28% p.a. (EIR from 1.92% p.a.) and zero processing fees. Terms and conditions apply. | 15 Oct 2026 till 31 Dec 2026 |
| GXS FlexiLoan | From 1.00% p.a. | From 1.84% p.a. | Get 1.88% off your interest rate as cashback by naming your loan "MSDEAL". Terms and conditions apply. | 1 Jun 2026 till 30 Nov 2026 |
💡 MoneySmart Tips
- Rates quoted are illustrative and depend on your credit profile and loan tenure.
- Cashback, SmartPoints or reward fulfilment timelines vary per lender and campaign.
- Rewards are valid for applications via MoneySmart only unless otherwise stated.
- Always refer to the full terms and conditions provided by the lender and application platform.
💡 MoneySmart Tip
A traditional bank loan usually offers some of the lowest effective interest rates, though they also tend to have stricter eligibility requirements.
Digital banks have become increasingly competitive and can be just as affordable, often providing a strong middle ground with fast approvals, low fees, and app-based convenience.
In contrast, licensed moneylenders typically carry much higher EIRs and lower loan limits tied to your income level, making them best reserved for urgent, short-term borrowing.
Always use MoneySmart to compare across providers and secure the most cost-effective option.
Personal Loan Lenders in Singapore: Banks vs Digital Banks vs Moneylenders
| Provider type | Examples | Typical tenure | Typical loan size | Watch out for |
|---|---|---|---|---|
| Banks | DBS Personal Loan, CIMB Personal Loan, Standard Chartered CashOne, UOB Personal Loan, OCBC ExtraCash Loan, HSBC Personal Loan | Up to 5 years |
Minimum: $500 to S$1,000 Maximum: Up to S$200,000 (DBS, CIMB) to S$250,000 (SCB); subject to income |
Processing or annual fees; early repayment fees |
| Digital banks | GXS FlexiLoan, Trust Instant Loan, MariBank Instant Loan | Varies by lender; GXS FlexiLoan: 2 to 60 months per drawdown |
From S$100 to up to S$100,000 Often drawn from a credit limit you hold with the bank |
Late interest of about 28% to 31% p.a. on overdue amounts; early repayment fees at some |
| Licensed moneylenders | Best Licensed Moneylender Personal Loan, Cash Direct, Credible.sg, Trillion Credit Solutions | Shorter, e.g. up to 36 months | Capped by law at 6 times monthly income across all moneylenders (if you earn S$20,000 or more a year) | Higher interest and admin fees |
Banks and digital banks are regulated by the Monetary Authority of Singapore (MAS). GXS FlexiLoan, for example, charges no processing, annual or early repayment fees, and funds reach your account within minutes.
Meanwhile, licensed moneylenders are regulated by the Ministry of Law's Registry of Moneylenders. They often accept borrowers who don't meet bank income rules, including foreigners on valid passes. By law, they can charge:
- Interest of up to 4% a month
- A late fee of up to S$60 for each month of late repayment
- An admin fee of up to 10% of the loan principal
Total charges can never exceed the amount you borrowed.
💡 MoneySmart Tip: Always check a lender against the Registry's list of licensed moneylenders before you borrow. Licensed moneylenders can't advertise by SMS, so unsolicited loan texts or calls are likely from unlicensed lenders. Never share your Singpass ID or password with any lender.
Personal Loan Costs: Interest Rates, EIR, and Fees
The advertised interest rate is only part of the cost. Compare loans on their effective interest rate (EIR), which builds the repayment schedule and mandatory fees into one annual rate.
- Interest rate: A flat annual rate on the original loan amount, from under 1% p.a. at banks and digital banks
- Processing or admin fee: None to about 1% of the loan at banks and digital banks, and up to 10% at licensed moneylenders; usually deducted from the cash you receive
- Annual fee: None on many loans, but for some, it can be up to S$200 in the first year
- Late fees: Around S$100 to S$130 per missed instalment at banks, and up to S$60 a month at licensed moneylenders
- Early repayment fee: Usually S$100 to S$250, or 3% of outstanding principal amount (whichever is higher), though some lenders charge none
Remember, short tenures push EIR up because fees are spread over fewer months. A 10% admin fee on a six-month loan raises the EIR far more than a 1% fee on a five-year loan.
💡 MoneySmart Tip: Use a loan repayment calculator to test different amounts and tenures. A longer tenure lowers your monthly instalment, but raises the total interest you pay. Keep your instalment within what your take-home pay can cover after essentials and savings.
How much does a S$10,000 personal loan cost a month?
At an advertised flat rate of 1.00% p.a., before fees:
| Loan tenure | Monthly instalment | Total interest |
|---|---|---|
| 12 months | S$841.67 | S$100 |
| 36 months | S$286.11 | S$300 |
| 60 months | S$175 | S$500 |
The rate you're offered depends on your credit profile, and fees raise the real cost. Keep your instalment within what your take-home pay can cover after essentials and savings.
Should You Take a Personal Loan?
| ✅ Yes, you can consider if… | ❌ No, you shouldn’t if… |
|---|---|
| The expense is planned and necessary (e.g. for wedding, renovations, medical bills) | You use it to cover the same budget gap every month |
| Consolidating a few high-interest debts into one loan with a lower EIR | You borrow to fund speculative investments such as trading or crypto |
| Replacing a costly payday-style borrowing with a longer, cheaper instalment loan | You take a new loan just to repay an old one, without changing your cash flow |
If you need cash urgently, check first whether the expense can be reduced, delayed or paid in instalments with the provider. Fast-approval instant loans still lock you into months or years of repayments, so compare the EIR and fees before you accept an offer.
💡 MoneySmart Tip: Late payments stay on your credit record and make future loans harder to get. If you can't stop borrowing, register for self-exclusion with the Moneylenders Credit Bureau to block most new moneylender loans.
Why MoneySmart is the Trusted Platform for Personal Loans in Singapore 👉
Why Choose MoneySmart?
- MAS-licensed and Ministry of Law approved lenders only
All partners are vetted, licensed, curated, and regulated by the Monetary Authority of Singapore and the Ministry of Law. - Trusted by thousands
Backed by user reviews and a strong track record of helping Singaporeans and expats secure financing through reliable applications. - Fast approvals as quick as 1 hour
Apply online and get results in as little as 1 hour with selected banks and licensed moneylenders. - Digital first
Apply seamlessly via SingPass/Myinfo for a fully online, paperless, and secure application from start to finish. - Inclusive options
Loans are available for Singaporeans, PRs, foreigners, and applicants with lower credit scores. - Flexibility for all applicants
Flexible criteria; personal loans available for a wide range of needs. Compare across banks and licensed moneylenders, all in one place.
See what customers have to say about applying Personal Loans with MoneySmart
13 Smart Ways Singaporeans and Expats Use Personal Loans
- Wedding expenses ➡ Best Wedding Loans in Singapore
- Home renovations ➡ Personal Loan Guides for Home Renovations
- Education & upskilling ➡ Best Education Loans in Singapore
- Medical bills & emergencies ➡ Best Emergency Loans in Singapore
- Credit card debt consolidation ➡ Debt Consolidation Plan
- For liquidity ➡ Emergency Cash Loans
- Car ownership & COE renewal ➡ Personal Loan Guides for Cars/COE
- Downpayment loan ➡ Personal Loans for Downpayment
- Expat needs ➡ Personal Loans for Foreigners in Singapore
- Loans for travel expenses ➡ Personal Loans for Travel Expenses
- Funeral costs ➡ Personal Loans for Funeral Expenses
- Vet bills ➡ Personal Loans for Vet Bills
- Investments (not recommended) ➡ Can You Use a Personal Loan to Invest in Singapore?
💡In general, personal loans are best for planned expenses with clear repayment ability. If you’re unable to comfortably repay your monthly instalments, taking up a personal loan could worsen your debt situation—and we strongly advise against borrowing irresponsibly. Always compare interest rates, fees, and tenure before applying, so your loan works for you, not against you.
Debt Consolidation Plan (DCP) vs Personal Loan
A Debt Consolidation Plan (DCP) combines your interest-bearing unsecured debts across participating banks into one loan with a single monthly repayment.
| ✅ Yes, you can consider if… | ❌ No, you shouldn’t if… |
|---|---|
| The expense is planned and necessary (e.g. for wedding, renovations, medical bills) | You use it to cover the same budget gap every month |
| Consolidating a few high-interest debts into one loan with a lower EIR | You borrow to fund speculative investments such as trading or crypto |
| Replacing a costly payday-style borrowing with a longer, cheaper instalment loan | You take a new loan just to repay an old one, without changing your cash flow |
Note: Renovation, education and medical loans can't be consolidated under a DCP. A DCP limits your access to new credit, but that also stops further debt from building up.
Personal Loan Eligibility and Documents
| Borrower profile | Minimum annual income | Typical documents required |
|---|---|---|
| Singapore Citizens and PRs |
From S$20,000: GXS FlexiLoan, CIMB Personal Loan From S$30,000: Standard Chartered CashOne, UOB Personal Loan (salaried only) |
NRIC, latest payslips, CPF contribution history or latest Notice of Assessment (NOA), often retrieved via Singpass MyInfo |
| Foreigners (work pass holders) |
From S$30,000: CIMB Personal Loan (Malaysians) From S$60,000: DBS Personal Loan From S$65,000: HSBC Personal Loan From S$90,000: Standard Chartered CashOne |
Passport (at least 6 months' validity), work pass, proof of income, such as payslips Proof of address, such as a utility bill or tenancy agreement |
| Self-employed or commission earners | From S$30,000: Standard Chartered CashOne, Trust Instant Loan | NRIC or work pass, latest NOA, bank statements showing your income |
| Licensed moneylender borrowers | Depends on the lender; loan size is capped by law based on income | NRIC, or passport and work pass, proof of address, proof of income, if available |
How to Apply for a Personal Loan in Singapore
Compare & shortlist loans
💡 Remember to look beyond the headline rates; check the EIR and fees reflecting the true cost of your loan.
Check eligibility
- Singaporeans/PRs: $10,000-$40,000
- Foreigners: $40,000-$60,000 with valid EP/S Pass.
- Usually ≥ 18 or 21 years old to apply
Prepare necessary documents
- Singaporeans/PRs: NRIC + payslips/CPF + proof of address
- Foreigners: Passport + EP/S Pass + payslips + employment contract + proof of residence (e.g. utility bills)
Apply for personal loan online via MoneySmart
You’ll also be prompted to submit your email address on our MoneySmart Rewards Form to qualify and track your sign-up reward upon applying through us.
Wait for loan application review and approval
Receive your loan disbursement funds
Monitor your SMS or email for confirmation and payment details.
No Payslip for Personal Loans? No Problem.
Need extra funds but don’t have a fixed monthly salary? Our guide shows you how freelancers, gig workers, and self-employed individuals in Singapore can qualify for personal loans, what documents you’ll need, and which lenders are most flexible.
FAQs About Personal Loans
What is a personal loan?
- A personal loan is an unsecured loan you repay in fixed monthly instalments over a set tenure, usually up to five years. As there's no collateral, lenders approve you based on your income and credit history. In Singapore, banks, digital banks and licensed moneylenders all offer personal loans.
What is EIR in a loan?
- EIR, or effective interest rate, is the true yearly cost of a loan. Unlike the advertised flat rate, it includes mandatory fees and accounts for your balance falling as you repay. EIR is therefore usually higher than the flat rate, and it's the fairest way to compare loans.
What are personal loan interest rates in Singapore?
Banks and digital banks advertise rates from under 1% p.a., but compare loans on their EIR:
- Banks and digital banks: EIR from about 1.75% p.a.
- Licensed moneylenders: interest of up to 4% a month, the legal cap
The rate you're offered depends on your income and credit profile.
Which bank is best for a personal loan in Singapore?
No single bank is best for everyone. The best personal loan for you has:
- The lowest EIR you qualify for
- A monthly instalment you can comfortably afford
- Low or no fees, including no early repayment fee if you might settle early
How much personal loan can I get from a bank?
It depends on your income and the lender:
- Banks: Usually 4 to 8 times your monthly income, up to S$200,000 to S$250,000
- Licensed moneylenders: Your total unsecured loans are capped at S$3,000 if you earn under S$20,000 a year (S$500 for foreigners earning under S$10,000), or 6 times your monthly income if you earn more
Can I get an instant personal loan in Singapore?
Yes. Many banks and digital banks offer instant loans applied via Singpass MyInfo almost straight away, and some pay out within seconds. In contrast, licensed moneylenders may take a few hours. Fast approval doesn't make a loan cheaper, so compare the EIR and fees before you accept.
Can foreigners get a personal loan in Singapore?
Yes, but foreigners have fewer options and need a higher income. Some banks and digital banks accept foreigners with a valid work pass, usually with a higher minimum income than for locals. Licensed moneylenders also lend to foreigners on valid passes. Compare personal loans for foreigners to see who qualifies.
Can I get a personal loan with bad credit?
Possibly, but expect smaller loan amounts and higher costs. Licensed moneylenders may approve borrowers that banks decline. No legal lender guarantees approval, so treat any guaranteed-approval offer as a red flag. Repaying on time rebuilds your credit score. If you've been rejected more than once, credit counselling can help you sort out your finances before reapplying.
Can I get a personal loan if I'm unemployed?
It's difficult, as most banks need proof of regular income. Licensed moneylenders may approve a small loan, but the law caps how much they can lend based on your income. A co-applicant with a steady income, or collateral, can help. Compare the best loans for unemployed borrowers and personal loans for low-income earners to explore your options.
Are payday loans legal in Singapore?
Yes, if the lender is licensed by the Ministry of Law. Payday loans face the same legal caps as other moneylender loans:
- Interest of up to 4% a month
- An admin fee of up to 10%
- A late fee of up to S$60 a month
Total charges can't exceed what you borrowed.